CRA notice of objection help for Canadian businesses

Reassessed by CRA and you disagree? Check your notice free, see exactly how long you have to object, and have it handled by a firm led by a CPA with 10 years of CRA audit experience. Income tax and GST/HST, for businesses and their owners across Canada.

Check Your Notice Free

Confidential. No obligation. We tell you whether an objection is worth filing before you commit to anything.

10 years of CRA audit experience
CPABC licensed CPA firm
Income tax and GST/HST disputes
Businesses across Canada

Check your CRA notice before you do anything else

Upload the letter you received. You'll get the basics right away: what the letter means, whether you can object, your deadline, how collections and interest work, and how to file. Then email it to Brookside CPA for a free, confidential review.

Your letter is read on your own device and is never uploaded. You decide whether to email it to us, and everything you share is confidential.

What the check reads

  • The type of letter. A notice of assessment or reassessment, a proposal letter, a statement of account, or a review request.
  • The tax program. Corporate income tax, GST/HST, payroll or personal tax, from the account number on the letter.
  • Dates and amounts. The date on the notice, the tax year or reporting period, and the amount owing.
  • Penalty and issue wording. Gross negligence penalties, denied input tax credits, shareholder benefits, net worth assessments, self-supply and late-filing penalties.

What you get back

  • Right away: what the letter means, whether you can object, your deadline and extension window, the amount, how collections and interest work, how to file, and the official CRA forms.
  • When you ask for a review: the page creates one file with your report and your letter, and you email it to Brookside CPA. We read it and tell you whether you have grounds to object and how to build the objection.
  • Then, if you'd like: book a free 15-minute call to go through your letter with us.

Objection deadlines and rules by tax type

Income tax and GST/HST objections follow different rules, and the gap matters most for cash flow. Count every deadline from the date printed on the notice.

RuleCorporate income tax (T2)GST/HSTPayrollPersonal income tax (T1)
Deadline to object90 days after the notice date90 days after the notice date90 days after the notice dateLater of 90 days after the notice or one year after the filing due date
How to fileMy Business Account or Form T400AMy Business Account or Form GST159Form T400A for income tax withheld. CPP and EI through an appeal to the MinisterMy Account or Form T400A
Collections while you objectGenerally held until 90 days after the decision. Large corporations pay half.Not held. CRA may postpone or accept security, at its discretion.Not held for amounts that should have been withheld.Generally held until 90 days after the decision.
Tax Court if Appeals hasn't decidedAfter 90 daysAfter 180 daysAfter 90 daysAfter 90 days
Extension of timeUp to one year after the deadlineUp to one year after the deadlineUp to one year after the deadlineUp to one year after the deadline

What a CRA notice of reassessment means

A notice of reassessment is CRA's decision to change a return it has already assessed, usually after an audit or review. It replaces the earlier assessment, and the new balance is legally owing from the date on the notice, even if the reassessment is wrong.

It stays in force until it's changed, and the formal way to change it is a notice of objection. Calling the auditor or mailing your records again won't reopen the file on its own.

CRA can normally reassess within three years of the original notice for individuals and Canadian-controlled private corporations, and four years for other corporations. For GST/HST, the limit is generally four years from when the return was due or filed. After that, it has to show a misrepresentation caused by carelessness, neglect or wilful default, or fraud. That burden is on CRA.

Three things start the day it's sent

  • The objection clockFor businesses, 90 days from the date on the notice. Individuals may have longer.
  • InterestArrears interest compounds daily at CRA's prescribed rate on anything unpaid, including amounts you're disputing.
  • CollectionsIncome tax collection is generally held once you object. GST/HST and payroll amounts can be collected right away.

What you can do after a reassessment

An objection isn't always the right move. Match your situation to the route that fits.

The reassessment is right, and you owe the money

Pay it, or set up a payment arrangement

Paying stops interest from growing. If you can't pay in full, contact CRA about an arrangement before collections escalate.

CRA made a processing error, like a misapplied payment or a missed slip

Ask CRA to correct it

A payment search or an adjustment request is often faster than an objection. File an objection as well if the deadline is close.

You disagree with the tax, the penalty, or both

File a notice of objection

Online through My Business Account or My Account, or with Form T400A for income tax or Form GST159 for GST/HST, before the deadline.

The 90 days have already passed

Apply for an extension of time

Available for one year after the deadline if you meant to object on time or couldn't act, and you apply as soon as you can.

You accept the tax, but penalties and interest came from circumstances beyond your control

Request taxpayer relief

A separate request on Form RC4288 asks CRA to cancel or reduce penalties and interest. It can run alongside an objection.

Appeals confirmed the reassessment and you still disagree

Appeal to the Tax Court of Canada

You have 90 days from the decision. Smaller disputes can use the informal procedure, which is simpler and has no filing fee.

How the CRA objection process works

From the audit to the Tax Court, a dispute moves through the same six stages. Knowing which one you're in decides what you can do next.

  1. 1

    Before the notice

    Proposal letter

    The auditor sets out proposed changes and invites a response, usually within 30 days. You can't object yet, but your response can change the result.

  2. 2

    Day 0

    Notice of reassessment

    The changes become an assessment. The objection clock starts on the date printed on the notice.

  3. 3

    By day 90

    Notice of objection

    Filed online or with Form T400A (income tax) or GST159 (GST/HST), setting out the facts, the reasons and the documents.

  4. 4

    Months, not weeks

    Appeals review

    An appeals officer, separate from the auditor, reviews the file. CRA's recent averages run about four months for simpler files and about a year for most business disputes.

  5. 5

    Decision

    Confirm, change or cancel

    Appeals confirms the reassessment, varies it, or vacates it, and sends a notice of confirmation or a new reassessment.

  6. 6

    Within 90 days of the decision

    Tax Court of Canada

    If you still disagree, you can appeal. If Appeals hasn't decided, you can go after 90 days for income tax or 180 days for GST/HST.

Missed day 90? You can apply for an extension of time for up to one year after the deadline, and file the objection with it. Check your deadline.

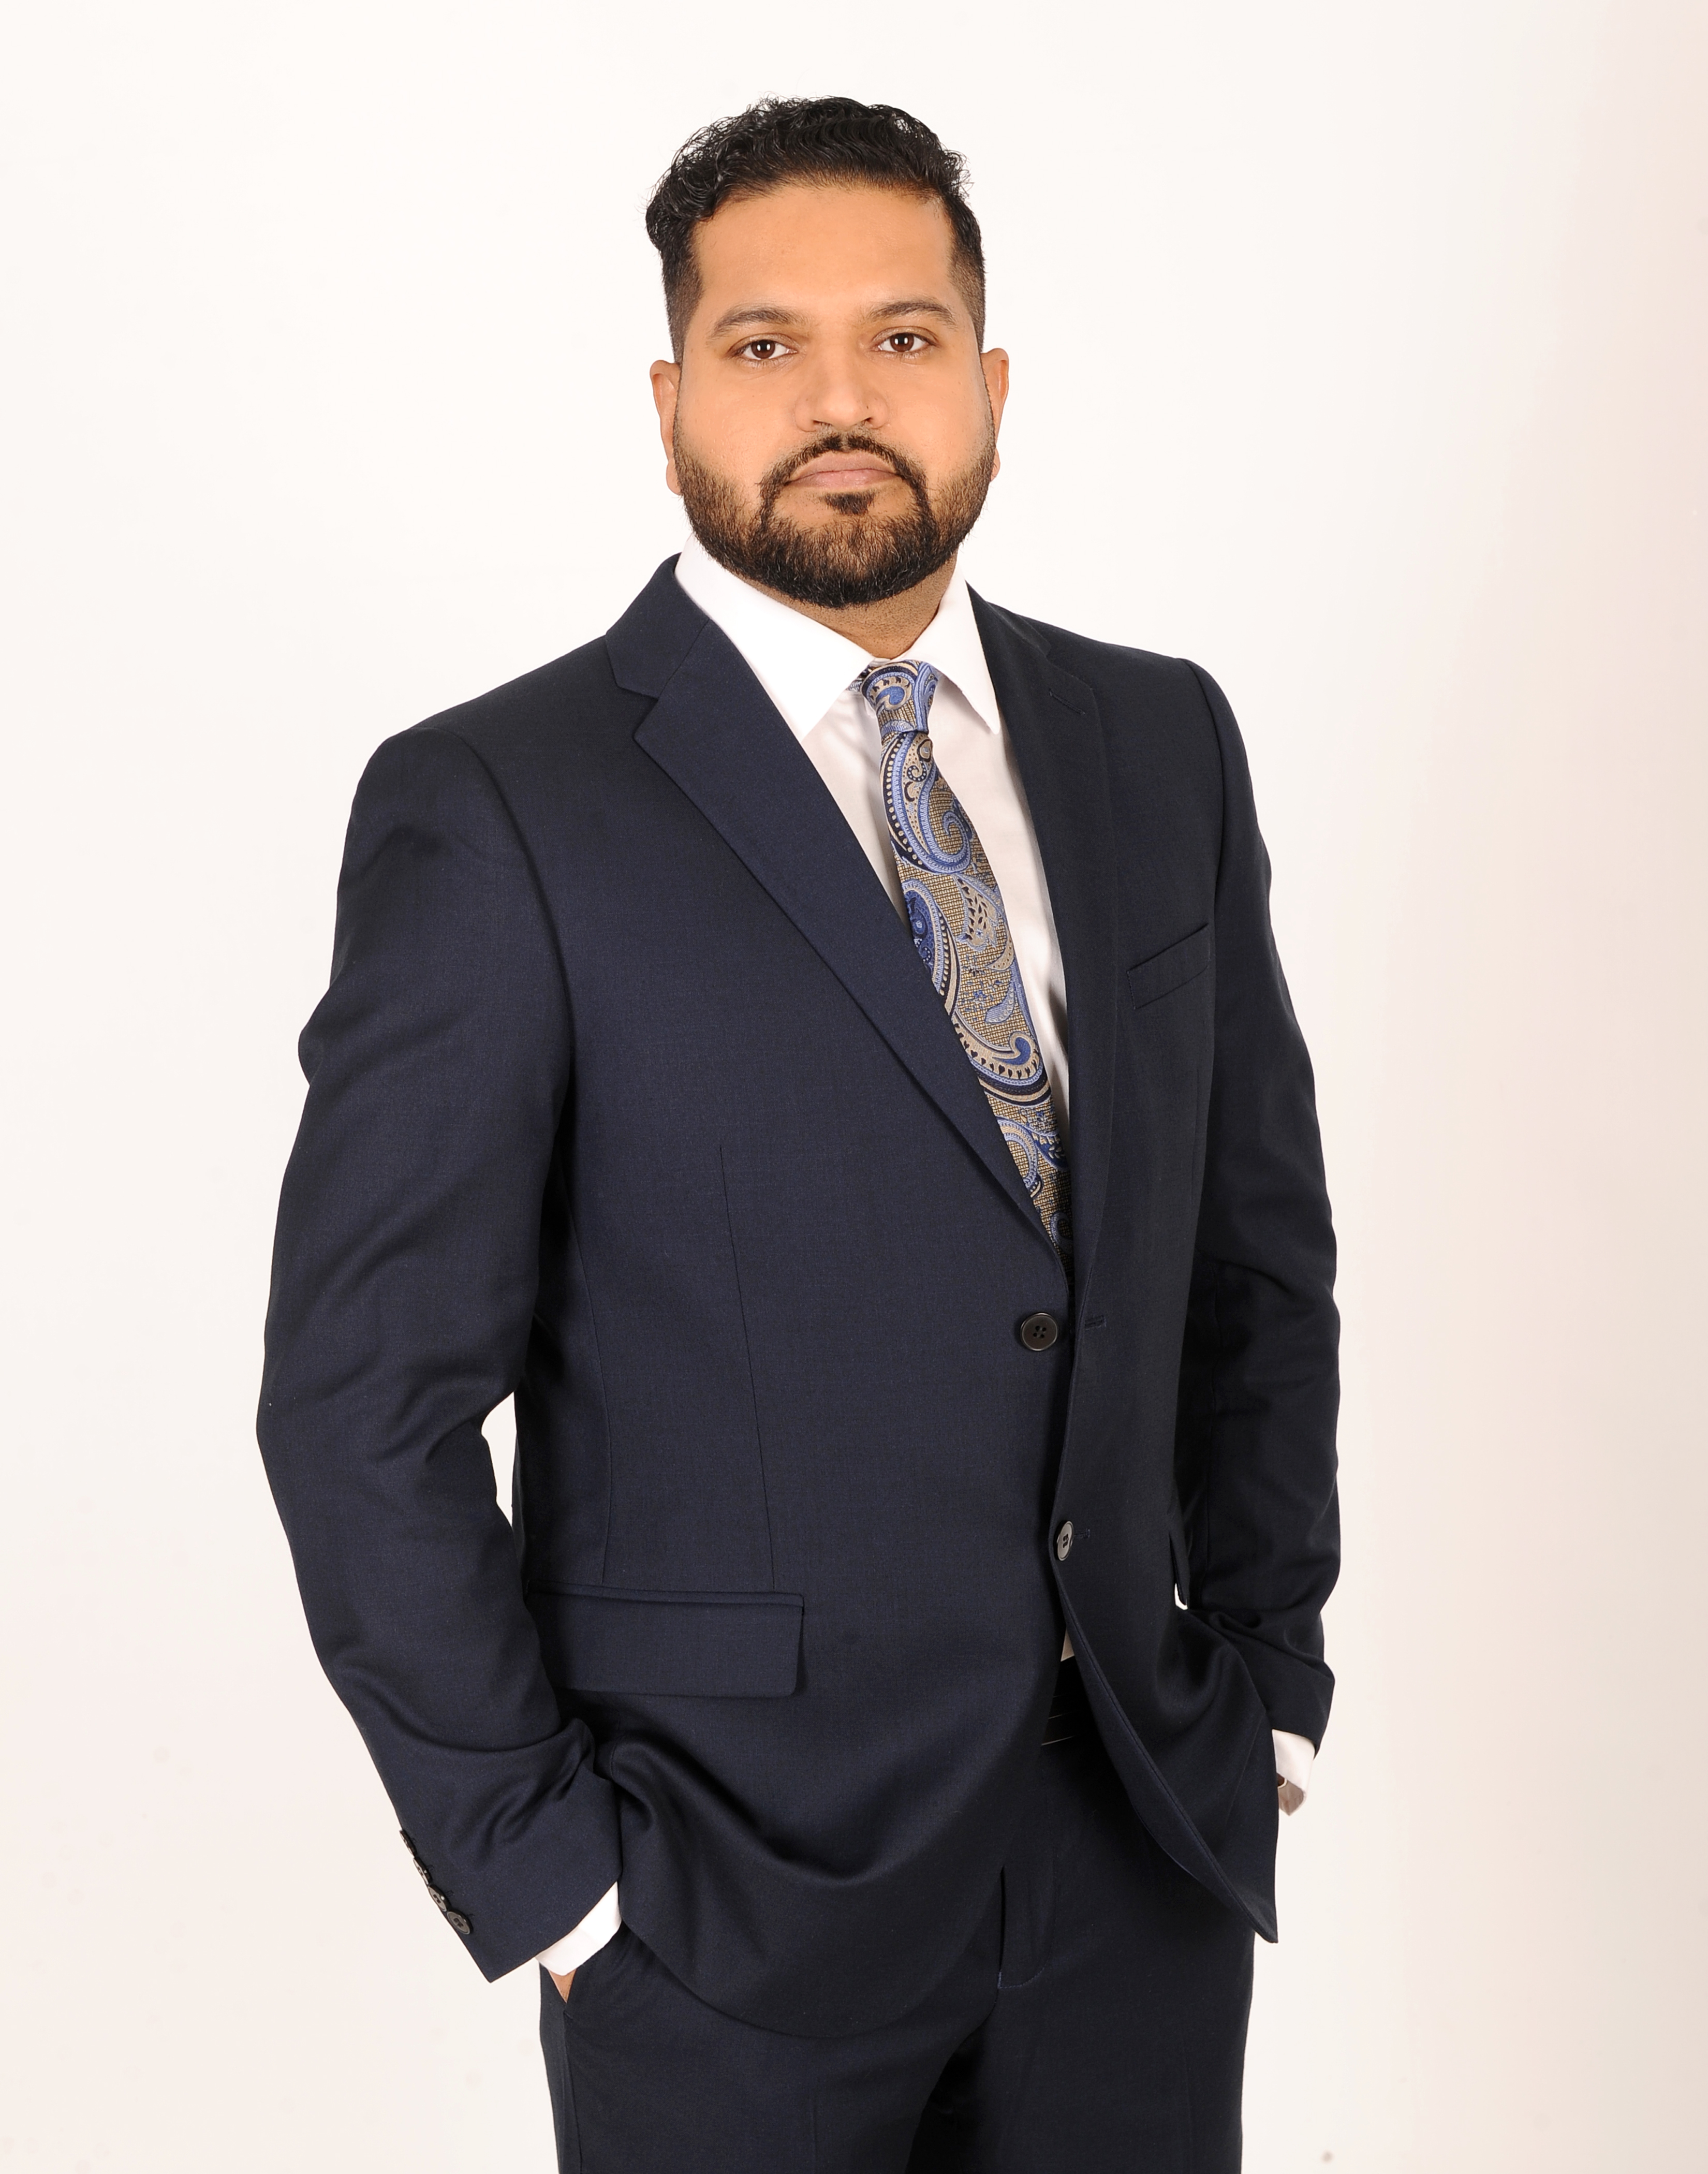
Parm Shergill, CPA, principal of Brookside CPA, former CRA auditor
Parm Shergill, CPAPrincipal, Brookside CPA
10years of CRA
audit experience
Income tax and GST/HSTObjections for businesses across Canada

Ten years inside CRA audit, now on your side of the file

Brookside CPA is led by Parm Shergill, a CPA with 10 years of CRA audit experience. He built audit files from the auditor's side, so we know how a reassessment is put together, where the working papers are thin, and which positions hold up when an appeals officer reviews them.

That changes what we do first. Before we write a word of your notice of objection, we get CRA's own file and read it the way Appeals will. Most of the argument is already sitting in the auditor's working papers.

We handle income tax and GST/HST objections for corporations and their owners across Canada, with particular depth in construction, real estate development and owner-managed businesses.

How we handle your objection

  1. 1

    Get CRA's file

    We request the audit report and the auditor's working papers, so we can see how every adjustment was calculated and where it's weakest.

  2. 2

    Check the risk before filing

    We confirm the deadline, which years are still open, and whether an objection could invite a wider review.

  3. 3

    Build it issue by issue

    Each adjustment gets the facts, the section of the Income Tax Act or Excise Tax Act that applies, and the documents that prove it.

  4. 4

    Deal with Appeals for you

    We handle every call and letter with the appeals officer, including settlement talks, and bring in tax counsel if the file needs to go to court.

Reassessments that are often reduced on objection

Appeals changes an assessment when the facts, the law or the math don't support it. These are the areas where businesses most often have a case.

  • Input tax credits denied on documentation

    Credits are often denied because an invoice is missing a GST/HST number or names the wrong entity. Contracts, supplier confirmations and other records frequently contain the required information.

  • Net worth and bank deposit assessments

    When records are incomplete, CRA may estimate income from deposits or changes in net worth. Transfers, loans, gifts and non-taxable receipts are often counted as income, and each one traced reduces the assessment.

  • Shareholder benefits

    Personal use of company funds or assets can be assessed twice: the expense is denied to the company and a benefit is added to the owner. Both sides need an answer, and the amounts are often overstated.

  • Gross negligence penalties

    A gross negligence penalty needs more than a mistake, and CRA has to prove it. You can object to the penalty even if you accept the tax.

  • Years that shouldn't have been reopened

    Past the normal reassessment period, CRA has to show carelessness, neglect, wilful default or fraud. That burden is on CRA, and it isn't always met.

  • New home and self-supply assessments

    Builders who rent out or move into homes they built can face GST/HST self-supply assessments. These usually turn on fair market value and timing, and both can be challenged with evidence.

  • Records the auditor didn't review

    If documents you provided were overlooked, an objection puts them in front of an appeals officer. We tie each document to the adjustment it answers so it can't be missed.

  • Arithmetic and allocation errors

    Adjustments applied to the wrong period, entity or account, or counted twice across years, are more common than people expect and are often the quickest wins.

What to send us

Whatever you have is enough to start. We'll ask for the rest.

  • The notice of reassessment, and any earlier notices for the same period
  • The proposal letter and audit report, if you received them
  • Anything you sent to the auditor during the audit
  • Records behind the amounts you disagree with, such as invoices, contracts and bank statements

How Brookside CPA helps with reassessments like these

Four reassessments we see often, what CRA got wrong, and how we build the objection that gets them reversed.

Illustrative examplesBased on the kinds of files we handle, not reports of specific client results. No names, amounts or identifying details, and every file turns on its own facts.

GST/HST, contractor

Input tax credits denied over missing GST/HST numbers

The reassessment

A framing contractor's GST/HST audit disallowed input tax credits on a long list of subcontractor invoices that didn't show a GST/HST number, and added a gross negligence penalty on top.

Why CRA got it wrong

The subcontractors were registered, and their GST/HST numbers were on the signed subcontracts and monthly statements already in the file. The required details can come from more than one document, and a paperwork gap isn't gross negligence.

How Brookside CPA helps

We match every disallowed invoice to the subcontract and statement that carry the number, confirm each number in CRA's GST/HST registry, and argue the penalty separately, because for gross negligence the burden of proof is on CRA.

Result in this exampleInput tax credits allowed and the penalty cancelled.
Income tax, owner-manager

Bank deposits treated as unreported income

The reassessment

CRA ran a bank deposit analysis on an owner-manager and his company, treated every deposit it couldn't explain as income, and added a gross negligence penalty.

Why CRA got it wrong

Many of the deposits were never income: transfers between his own accounts, repayments of money he had lent the company, a family loan, and the sale of a personal vehicle.

How Brookside CPA helps

We trace each deposit to its source with bank records, loan documents and the bill of sale, and lay them out in the auditor's own schedule format so Appeals can check them line by line.

Result in this exampleAdded income cut to the small amount left unexplained, and the penalty removed.
GST/HST, home builder

Self-supply tax on a home the builder rented out

The reassessment

A builder rented out a new home instead of selling it. CRA assessed GST/HST on the self-supply using a value drawn from listing prices at the peak of the market.

Why CRA got it wrong

Self-supply is valued when the home is first rented or occupied, not at list prices from another point in the market. The builder also qualified for the new residential rental property rebate and hadn't claimed it.

How Brookside CPA helps

We support the value with an appraisal dated to the first lease and comparable sales from that month, and file the rental property rebate alongside the objection.

Result in this exampleValue brought back to market on the right date, with the rebate recovered.
Income tax, late objection

The 90-day deadline was missed

The reassessment

A business owner was reassessed after a review letter that never reached him. He kept calling CRA to dispute it, the 90 days passed, and collections started.

Why the file wasn't lost

The law allows an extension of time for up to a year if you meant to object on time and applied as soon as you could. His call records showed exactly that.

How Brookside CPA helps

We file the extension application and the full objection together, with a dated log of every call and letter, then ask collections to hold as soon as the extension is granted.

Result in this exampleExtension granted, collections paused, and the objection heard on its merits.

Recognise your situation in one of these?

Check Your Notice Free

CRA notice of objection questions

What is a CRA notice of objection?

A notice of objection is the formal way to dispute a CRA assessment or reassessment. It sends your file to CRA's Appeals Branch, which reviews it independently of the auditor and can confirm, change or cancel the assessment. For income tax it's filed online or with Form T400A, and for GST/HST online or with Form GST159.

Can a CRA reassessment be reversed?

Yes. Appeals can cancel or reduce a reassessment when the facts, the law or the calculations don't support it. Common examples are input tax credits denied over paperwork that other records cover, bank deposits counted as income that were never income, and penalties CRA can't prove.

How long do I have to file a notice of objection?

For corporations, GST/HST and payroll assessments, 90 days after the date CRA sent the notice. Individuals have until the later of 90 days after the notice or one year after their filing due date for that tax year. Count from the date printed on the notice, not the day it arrived.

How do I file a notice of objection with CRA?

Online through My Business Account, My Account or Represent a Client, using the formal dispute option, or by mail using Form T400A for income tax or Form GST159 for GST/HST. Set out each issue you disagree with, the facts and reasons, and attach the documents that support your position.

What should a notice of objection include?

Each adjustment you disagree with, the result you're asking for, the relevant facts, the reasons under the law, and the supporting documents. Objections that only say you disagree rarely succeed. Large corporations must also describe each issue and the amount of relief sought, and are limited to those issues if the file goes to court.

I missed the 90-day deadline. Can I still object?

Often, yes. You can apply for an extension of time up to one year after the objection deadline. You'll need to show that you intended to object on time or couldn't act, that you applied as soon as circumstances allowed, and that granting it is just and equitable. File the objection together with the request.

Do I have to pay CRA while my objection is under review?

For income tax, CRA generally can't collect the disputed amount until 90 days after Appeals decides, although large corporations pay half and payroll withholdings aren't postponed. GST/HST is payable right away, and CRA can collect it while you object unless it agrees to postpone collection or accepts security. Interest runs either way, so some businesses pay and object at the same time.

How long does a CRA objection take?

CRA publishes average processing times every month. Recently, simpler income tax objections have averaged around four months, and medium-complexity files, which include most business disputes, around a year. If Appeals hasn't decided within 90 days for income tax or 180 days for GST/HST, you can take the matter to the Tax Court instead.

What's the difference between a proposal letter and a notice of reassessment?

A proposal letter comes during the audit and sets out changes CRA intends to make. You respond to it, usually within 30 days, but you can't object to it. A notice of reassessment is the decision itself, and it's the document that starts the objection clock.

Can CRA reassess a year after three years?

CRA can normally reassess within three years of the original notice for individuals and Canadian-controlled private corporations, and four years for other corporations. For GST/HST, the limit is generally four years from when the return was due or filed. After that, CRA must show a misrepresentation due to carelessness, neglect or wilful default, or fraud, and the burden of proof is on CRA.

CRA ignored the documents I already sent. What now?

Resending them to the same area rarely helps. A formal objection moves the file to an appeals officer who reviews it independently. Attach the documents and explain which adjustment each one answers. If the problem is a payment CRA didn't apply, ask for a payment search first, since that's usually faster.

Can I object to a penalty but not the tax?

Yes. An objection can target the tax, the penalty, or both. For a gross negligence penalty, CRA has to prove the facts that justify it. Penalties and interest can also be addressed through a separate taxpayer relief request on Form RC4288.

Can filing an objection make my assessment worse?

It can. If the year is still within the normal reassessment period, CRA can look at other items while reviewing the file. That's why we check the file for exposure before anything is filed.

What happens if Appeals confirms the reassessment?

You have 90 days from the notice of confirmation to appeal to the Tax Court of Canada. Smaller disputes can use the informal procedure, which is simpler and has no filing fee. Larger or more complex appeals use the general procedure, where a corporation is normally represented by a lawyer.

Do I need a tax lawyer or a CPA for a CRA objection?

Most objections turn on facts, records and calculations, which is accounting work, so a CPA with audit experience is often the practical choice at the objection stage. If a file is headed for the Tax Court's general procedure or there's any criminal exposure, a tax lawyer should be involved. Communications with a lawyer can be privileged, while communications with an accountant generally aren't. We work alongside counsel when a file needs it.

What happens after I upload my notice?

Right away you get the basics: what the letter means, whether you can object, your deadline and extension window, the amount, how collections and interest work, how to file, and links to the official CRA forms. If you want Brookside CPA to review it, add your name, email and phone. The page creates one PDF with your details, the report and your letter, then opens an email to Brookside CPA with everything filled in. You attach the file and send, and a booking window opens for a free 15-minute call.

Is it safe to upload my notice on this page?

Yes. Your letter is read on your own device and is never uploaded to us or anyone else. If you ask for a review, the page creates your review file on your device and you choose to email it to us. Everything you share is kept confidential and used only to review your notice and contact you.
Your 90 days started on the date of the notice

The sooner we see it, the more of that time goes into building your case instead of chasing documents.

Check Your Notice Free